
One of the key disadvantages of investing in gold is that gold doesn’t pay you any income, so you only make money if the price goes up. Gold also comes with costs and risks, and you can plan for each one.
Summary of the disadvantages of investing in gold
| Downside | What it costs you | What you can do |
| No income | You don’t earn interest or dividends while you hold gold | Hold gold next to investments that pay income |
| Price swings | The price can drop quickly, and gold has had losing years | Buy in smaller amounts over time |
| Lower returns than stocks for long stretches | Gold can earn less than stocks for many years | Judge gold over decades, since the answer changes with the start year |
| Inflation | In many years gold has not kept up with rising prices | Plan to hold gold for years, not months |
| Premium and spread | You pay more than spot when you buy and get less when you sell | Get the full price in writing and compare sellers |
| Harder to sell | Selling gold takes more steps than selling a stock | Find out how a dealer’s buyback works before you buy |
| Storage and insurance | Costs for a safe, a bank box or a depository, and for insuring the shipment | Insure the shipment and pick your storage before you buy |
| Taxes | Profits on coins can be taxed at a higher rate than stocks | Know the rate before you sell |
| Scams | Pressure sales and fake offers can cost you your money | Don’t send money until you have the full price in writing |
Gold doesn’t pay you income
Gold doesn’t pay interest or dividends. A stock can pay you a dividend and a bond pays you interest, but gold only gives you a return when you sell it for more than you paid.
Warren Buffett described this in his 2011 shareholder letter: “if you own one ounce of gold for an eternity, you will still own one ounce at its end.” In the same letter he put gold in a group of “assets that will never produce anything, but that are purchased in the buyer’s hope that someone else … will pay more for them in the future.”
If you want regular income from your savings, hold gold next to stocks and other investments that generate cash flow. Swiss America recommends gold as a hedge, not as a whole plan.
Gold prices can go up and down quickly
Gold has had more losing years than stocks. In NYU Stern’s yearly returns data, gold had a losing year 19 times out of 55 from 1971 to 2025. The S&P 500 with dividends had 11 losing years over the same stretch, and 3 month Treasury bills had none.
The Commodity Futures Trading Commission (CFTC) says gold and other precious metals “are highly volatile and past performance is not a good predictor of future returns.” The price moves with supply and demand, inflation expectations, the strength of the dollar, world events and the prices of other commodities. Because so many things move the price, you can’t know what gold will be worth on the day you want to sell. It could be lower than what you paid.
We recently talked about gold pulling back from its highs on our podcast:
You can make price swings easier to live with if you buy in smaller amounts over time. When you buy a little at a time, some of your purchases will be at higher prices and some at lower prices, so you won’t put all of your money in at one price.
Gold can earn less than stocks for many years
Whether gold or stocks come out ahead depends on the year you start measuring from. Over 55 years, stocks came out ahead. Over the last 20 years and the last 10 years, gold did.
Here’s how gold compares with stocks, bonds, Treasury bills and inflation over four periods:
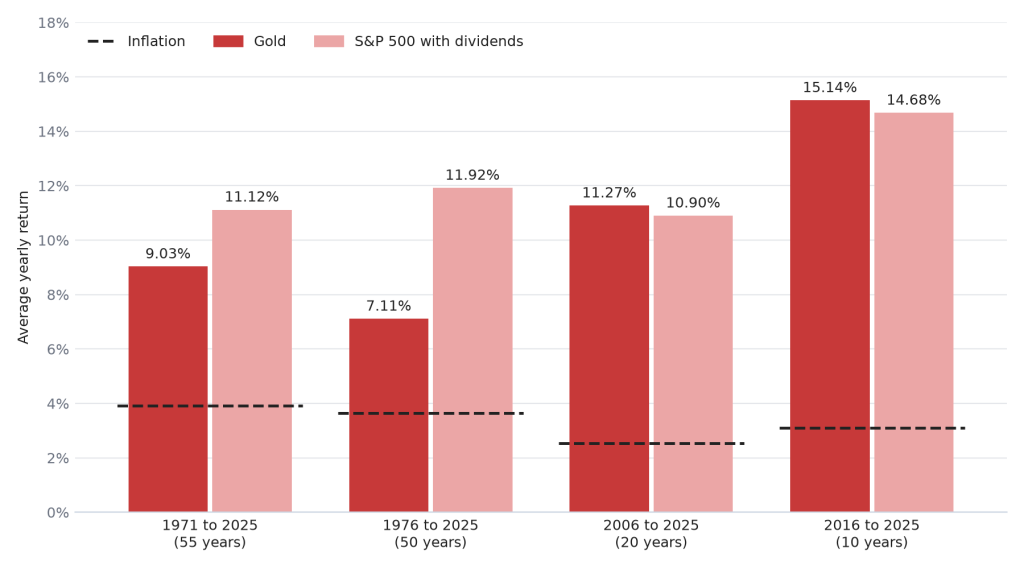
Each figure is the average yearly return, compounded, calculated from NYU Stern’s historical returns data (updated January 5, 2026). Inflation data is from the Federal Reserve Bank of Minneapolis annual average consumer price index.
Gold’s average yearly return changed from one period to the next. Here it is for six periods, from the same NYU Stern data:
| Period | Gold’s average yearly return |
| 1971 to 1980 | 31.77% |
| 1981 to 1990 | -4.15% |
| 1991 to 2000 | -3.36% |
| 2001 to 2010 | 17.74% |
| 2011 to 2020 | 3.01% |
| 2021 to 2025 | 18.07% |
From the end of 1980 to the end of 2000, gold lost 53.5% of its value in dollars. Gold’s year end price in 1980 wasn’t beaten again until the end of 2006, which is 26 years later. Its year end price in 2012 wasn’t beaten until the end of 2020. These prices are not adjusted for inflation.
If you buy gold, plan to hold it for the long-term.
Gold doesn’t always keep up with inflation
Many people buy gold to protect their savings from rising prices. Over 55 years it has done that, as the table above shows.
Year by year, the picture is less steady. Gold’s return was lower than that year’s inflation rate in 24 of the 55 years from 1971 to 2025. The S&P 500 with dividends fell behind inflation in 14 of those years. From 1994 to 2001, gold fell behind inflation every year. It did so again in 2013, 2014 and 2015.
Gold has protected buying power over the long run, not in every year.
You pay a premium when you buy and get less when you sell
When you buy gold coins or bars from a bank or a dealer, you pay the spot price plus a markup, which is called the premium. When you sell, you get the dealer’s buyback price, which is lower than the price the dealer sells at. The gap between the two is called the spread.
The premium and the spread both cost you money. The CFTC says the spot price has to rise enough to cover the premium plus any costs of selling before you make money. It also says premiums, fees and commissions can take away the profit from a purchase.
Before you buy, ask for the full price in writing.
Gold is harder to sell than stocks
Most stock trades settle one business day after you sell. Selling gold takes more steps.
If you sell back to Swiss America, here’s how it works:
- You ask us for a quote
- You mail your metals back and we inspect them to confirm they are valid
- We send you the funds
This covers coins and bars, including metals in a Gold IRA.
Storing and insuring gold costs
Physical gold needs secure storage. You can store it in:
- Home safe
- Bank safe deposit box
- Depository
A home safe costs money to buy, and you’re the one responsible for keeping it secure. If you use a bank box, keep in mind the FDIC doesn’t cover safe deposit boxes or what’s inside them, so check with your insurance provider about coverage.
Depositories charge storage fees. As an example, inside a Gold IRA at Gold Star Trust, commingled storage costs $125 a year and segregated storage costs $225 a year at minimum.
Outside an IRA, your metals ship to you, or straight to a third party depository if you’d rather not keep them at home. All Swiss America orders include secure shipping, insurance and full documentation.
Profits on gold coins can be taxed at a higher rate
The IRS taxes net capital gains from selling collectibles, such as coins, at a maximum 28% rate. Most other long term capital gains max out at 20%.
Here’s what the difference looks like in dollars. If you sell coins for a $10,000 profit, a 28% rate means up to $2,800 in federal tax. At a 20% rate, the tax would be $2,000.
A Gold IRA is taxed under different rules. Certain gold, silver and platinum coins, and bullion of a certain fineness, held by a bank or an approved trustee are not treated as collectibles in an IRA.
Scams and pressure sales
The CFTC warns gold buyers about scams. It tells buyers to be very suspicious of: